Industry: Telco

Welcome Home: The Benefits of Unified Access to AI-Powered Decisioning + Data

EBOOK

Welcome Home: The Benefits of Unified Access to AI-Powered Decisioning + Data

What if your decisioning technology came with the same benefits as a smart home system?

Are you working with multiple products, vendors and UIs in order to make decisions? What if you could have a single user interface to manage all of your technology solutions and save you from a disjointed, incomplete view of the credit risk lifecycle?

Check out our latest eBook and discover how one unified solution for data and AI-powered decisioning can change the way you think about your risk strategy. And bring you to the forefront of tech innovation, just like today’s smart homes.

Learn how unified access offers:

  • Built-in controls to manage risk, security and identity
  • Preconfigured data integrations to get you up and running quickly and easily
  • Flexibility to expand as your needs evolve
  • Automation to improve efficiency and power better user experiences

Ready to get smarter?

The Ultimate Guide to Decision Engines

What is a decision engine and how does it help your business processes?

Read the Blog

RESOURCE LIBRARY

EBOOK Telco - FeatureIMG

How Telcos Can Get Ahead of Fraud Across the Subscriber Lifecycle

Ebook How Telcos Can Get Ahead of Fraud Across ...
Data Providers Blog

Practical Guide to Reviewing Your Data Providers

Ebook What’s Missing from Your Decision Stack? Smarter decisions ...
EBOOK KShape

One Portfolio, Two Economies

One Portfolio, Two Economies: Model Drift, Consumer Divergence, and ...
EBOOK Survey2026

Survey: 2026 Global Decisioning Survey

What are the key challenges and priorities for financial ...
Survey: 2025 Global Risk Decisioning Survey

Survey: 2025 Global Risk Decisioning Survey

Survey: 2025 Global Risk Decisioning Survey What are the ...
EBOOK: How Telcos Can Boost Revenue Without the Risk

EBOOK: How Telcos Can Boost Revenue Without the Risk

Dial Into Profit: How Telcos Can Boost Revenue Without ...
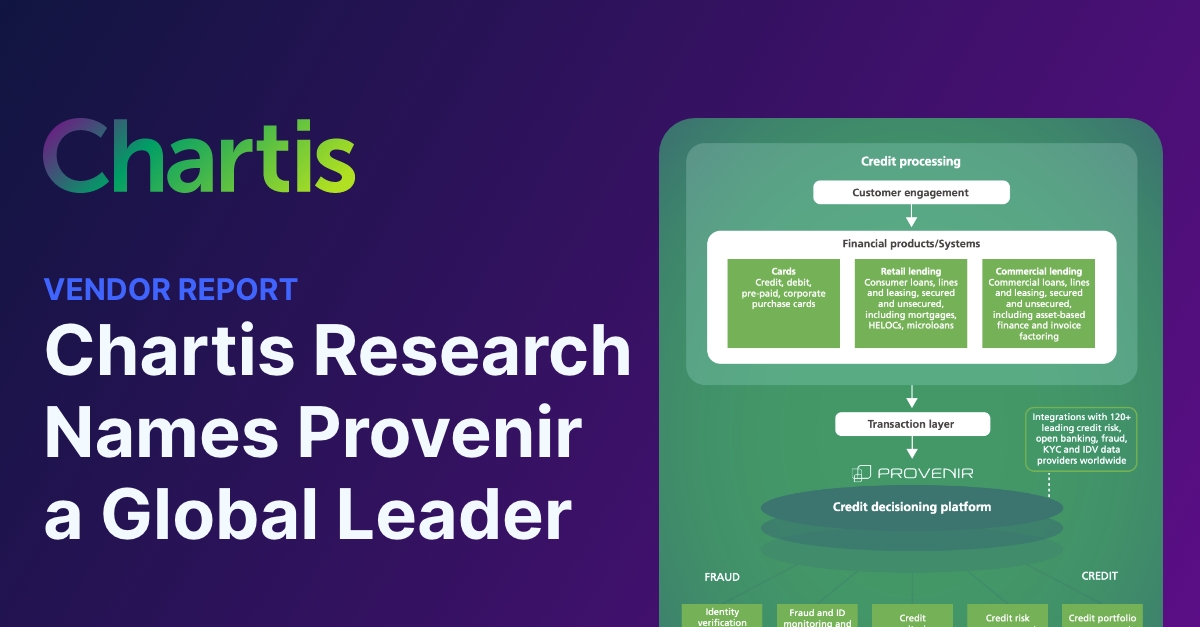
Vendor Report: Chartis Research Names Provenir a Global Leader

Vendor Report: Chartis Research Names Provenir a Global Leader

Chartis Research Names Provenir a Global Leader Credit and ...
Mind the Gap: The Need for Speedy, Accessible SME Lending in EMEA

Mind the Gap: The Need for Speedy, Accessible SME Lending in EMEA

EBOOK Mind the Gap: The Need for Speedy, Accessible ...

Continue reading

How Data Drives the Financing Shift in Telco

BLOG

How Data Drives the Financing Shift in Telco

As competition grows fiercer and products become commoditized, customers are placing more demands on their carriers. Forward thinking telco organizations are relying on advanced data and analytics to differentiate and hone their advantage.

This eight-page white paper presents data-driven insights and use cases to help you:

  • Dig into your credit risk data to improve finance offerings
  • Illuminate customer experience trends to reduce churn
  • Leverage alternative data to capture a broader market

“Provenir empowers the Telia Finance team to create and change credit offerings independently, process customer applications in seconds, and easily integrate into multiple data sources for better quality decisioning.”

Fredrik Nilsson, Telia Finance


LATEST BLOGS

260817 - BLOG Closing Fraud Gap - FeatureIMG - EN 61409

Beyond Detection: Cl...

Beyond Detection:Closing the Fraud Prevention Gap Financial services providers
260726 - BLOG eyeDP - FeatureIMG - 61058

Beyond Data: Why Dec...

Beyond Data:Why Decisioning Needs Document Intelligence Financial services providers
Fraud in Telco: Provenir Experts Answer Frequently Asked Questions

Fraud in Telco: Prov...

Fraud in Telco:Provenir Experts Answer Frequently Asked Questions 1.
260722 - ARTICLE Mike - FeatureIMG - 60958

AI governance in fin...

AI governance in financial services:What "governed" means in practice
Latam Compliance Challenge for Decisioning

LATAM Next Complianc...

From Data Protection to Decisioning Accountability:What LATAM Regulation Means
Banks Architecture Gap - Provenir

The Architecture Gap...

Decisioning ArchitectureThe Architecture Gap: Banking's Next Competitive Battleground Banks
BLOG Andy

The Real Cost of Ven...

The Real Cost of Vendor Dependency in Credit Decisioning
260617 - BLOG Matthew Nutt - FeatureIMG - 60431

What Does a Good Dat...

What Does a Good Data Provider Review Actually Look

Continue reading

3 Things Telcos Should Know About Alternative Data

BLOG

3 Things Telcos Should Know
About Alternative Data

Business models are changing — and rapidly.

Apologies, because you probably knew that.

But it’s happening much faster than we think, whether it is timed to product design shifts or concepts like the Internet of Things, or changed models like servitization. Some have even estimated that a standard enterprise business model changes every 2.5-3 years. The main revenue source may stay the same, but the plan underlying said revenue source shifts essentially every seven quarters.

Primarily a product-driven industry, we see this shift happening in Telco now. As devices become more expensive for an average consumer, telco caters to a built-in audience by way of financing offers. It’s somewhat of a servitization model in its own right: a product (the phone) bolstered by a service (the financing so that you can afford the phone over a period of time).

Financing makes sense as a new revenue stream for telco companies, but it opens up some new challenges too: namely, if you weren’t a lending institution before, how do you make decisions around financing and credit of different consumers? What if they have a non-existent credit history? What then?

Here arrives “alternative data.”

1. What is alternative data?

Don’t worry: it’s not like “alternative facts.”

The easiest definition: information that is not found in the files maintained by the three major credit reporting agencies. For example, some elements not kept in major CRA files include:

  • Telco
  • Utility information
  • Property record information
  • Social media footprints

Alternative data is actually a much bigger slice than you might think. Yes, 190 million Americans have a FICO score, and that’s by far the majority. But consider this: 28 million Americans are credit retired, new to credit, or lost access to credit — and 25 million have no credit bureau record. There’s more, too: while 92% of Americans have a cell phone, only 2.5% of consumer credit bureau files have telco information. It’s the same with utilities: 60% of U.S. residents pay utilities, but just 2.4% of files have this information.

Telco, utility, and lease/property information is often highly indicative of credit trustworthiness but just isn’t tracked at the conventional levels.

2. How do you pull alternative data?

Largely through public record data sources, although you can also search people’s social media profiles.

While social media is not as direct a correlation with credit trustworthiness, it can give you an idea of the person’s activities and habits, especially around check-ins. However, as more and more companies embed with Facebook, Twitter, Google, Instagram, et al. concerning immediate purchase (think “Buy Now” buttons), there will be more financial information tied to people’s social media accounts.

This concept is still getting to scale in the U.S., but one of the initial growth areas of alternative data was Indonesia, sometimes considered “the Twitter capital of the world.” There are 78 million active Internet users in Indonesia, with north of 50 million on both Facebook and Twitter. You won’t find that profile information in conventional lending approaches, no; but it’s still highly valuable.

Or is it?

3. Does alternative data work?

Yes. To wit: in one study where auto lenders decided to use alternative data in their decisioning processes, 40% of those rejected via “no-file” and 30% of those rejected via “thin-file” were found to have credit trustworthy scores when you considered these alternative data sources.

Is this a case of “not everyone is on the grid?” Yes, that’s part of it. The other part is that human existence is not stagnant. We’ve done things one way for so long when evaluating credit trustworthiness, but the world has changed dramatically, and we have access to much, much more information. Shouldn’t we be using it to make better decisions?

The Secret to Consumer Lending Success

Get the eBook


LATEST BLOGS
260817 - BLOG Closing Fraud Gap - FeatureIMG - EN 61409

Beyond Detection: Cl...

Beyond Detection:Closing the Fraud Prevention Gap Financial services providers
260726 - BLOG eyeDP - FeatureIMG - 61058

Beyond Data: Why Dec...

Beyond Data:Why Decisioning Needs Document Intelligence Financial services providers
Fraud in Telco: Provenir Experts Answer Frequently Asked Questions

Fraud in Telco: Prov...

Fraud in Telco:Provenir Experts Answer Frequently Asked Questions 1.
260722 - ARTICLE Mike - FeatureIMG - 60958

AI governance in fin...

AI governance in financial services:What "governed" means in practice
Latam Compliance Challenge for Decisioning

LATAM Next Complianc...

From Data Protection to Decisioning Accountability:What LATAM Regulation Means
Banks Architecture Gap - Provenir

The Architecture Gap...

Decisioning ArchitectureThe Architecture Gap: Banking's Next Competitive Battleground Banks
BLOG Andy

The Real Cost of Ven...

The Real Cost of Vendor Dependency in Credit Decisioning
260617 - BLOG Matthew Nutt - FeatureIMG - 60431

What Does a Good Dat...

What Does a Good Data Provider Review Actually Look
Continue reading