CS-ROI: Data Orchestration

Claire Hartley - APAC Compliance Challenge

APAC’s New Compliance Challenge

APAC’s New Compliance Challenge:
Managing Innovation Across a Fragmented Regulatory Region

Asia-Pacific is entering a more demanding phase of compliance, regulatory and data protection oversight.

The challenge is no longer simply keeping pace with new legislation. Organisations must now manage an increasingly complex combination of national privacy laws, data localisation requirements, international transfer restrictions, artificial intelligence governance and sector-specific regulation.

Unlike the European Union, APAC does not operate under one harmonised regulatory framework. Each jurisdiction has its own legal requirements, regulatory priorities and enforcement approach. A control that is appropriate in Singapore may not be sufficient in Australia, China, India, Indonesia or New Zealand.

This fragmentation creates a significant challenge for organisations operating across multiple APAC markets.

AI and Automated Decision-Making

Artificial intelligence is becoming inseparable from data protection and regulatory compliance.

In July 2026, Singapore’s Personal Data Protection Commission published guidance addressing how personal data should be collected and used throughout the generative AI lifecycle. This includes web scraping, reusing existing customer data, allocating responsibilities between AI providers and users, managing retention and responding to individual rights requests.

Australia is also introducing new transparency requirements for automated decision-making. From 10 December 2026, regulated organisations will need to disclose certain uses of personal information in computer-generated decisions that could significantly affect an individual’s rights or interests.

For financial services organisations, these developments create particular challenges. AI and automated models may influence credit, fraud, identity, affordability and customer-management decisions. Organisations must therefore be able to explain not only what a model does, but also how data is selected, how risk is assessed and where human oversight is applied.

Biometrics and Identity Data

Biometric information is also receiving greater regulatory attention.

New Zealand’s Biometric Processing Privacy Code introduces specific rules governing the collection and use of facial, fingerprint, voice, behavioural and other biometric information. Organisations already using biometric processing must transition to the new requirements by 3 August 2026.

This reflects a wider regional trend. Identity verification and fraud-prevention technology can deliver substantial benefits, but regulators increasingly expect organisations to demonstrate necessity, proportionality, transparency, security and appropriate retention.

Data Transfers and Local Requirements

Cross-border data transfers remain another major area of complexity.

APAC organisations frequently rely on global cloud infrastructure, regional service providers and international data sources. However, the legal mechanisms for transferring personal data differ significantly between jurisdictions.

Some countries require contractual safeguards. Others may require regulatory assessments, certifications, local storage or additional controls for particular categories of information. Organisations therefore cannot rely on one global transfer mechanism without first assessing the law, data and processing activity in each relevant market.

The practical challenge is knowing where information is located, how it moves, which providers can access it and which organisation is accountable at every stage.

How Provenir Meets These Demands

Provenir addresses these challenges through a global Compliance, Regulatory and Data Protection, or CRDP, framework that combines central governance with jurisdiction-specific regulatory analysis.

CRDP provides independent oversight and challenge across Provenir’s platform and works alongside Information Security, Product, Engineering, Technology and Legal. This enables regulatory requirements to be considered throughout product development, contracting, implementation and ongoing customer support rather than only at the final compliance review stage.

Provenir’s approach includes:

  • – privacy and data protection assessments for new technologies, products and processing activities;
  • – governance of international transfers, subprocessors and regional data flows;
  • – due diligence and risk assessment for vendors and data providers;
  • – defined incident identification, escalation, investigation and notification processes;
  • – data-minimisation, retention and access-control requirements;
  • – regulatory monitoring across the countries in which Provenir and its customers operate;
  • – documented accountability for AI, model governance and automated decision-making.

Provenir also uses a structured lines-of-defence model. Operational teams own and manage their controls, CRDP provides policy, advice, monitoring and challenge, and independent certification and assurance activity provides further scrutiny.

Privacy governance is embedded within how Provenir designs, deploys and operates its platform. This includes clear controller and processor role allocation, data-processing agreements, privacy impact assessments, international transfer safeguards, subprocessor oversight and breach-management procedures.

AI governance is similarly integrated across CRDP, Product, Engineering and Information Security. Provenir’s framework addresses purpose, accountability, data governance, fairness, transparency, human oversight, security and continuing monitoring, with reference to ISO/IEC 42001 and emerging regulatory requirements.

The platform itself supports this governance approach by bringing data, models and decisioning into a controlled environment. This gives customers greater visibility over decision strategies, testing, deployment and performance, while allowing them to apply their own regulatory policies and risk controls.

From Compliance Obligation to Market Confidence

The most successful organisations in APAC will not be those that attempt to apply one policy everywhere.

They will be those that establish consistent global governance while retaining the flexibility to respond to local laws, regulatory expectations and customer requirements.

For Provenir, strong CRDP governance is not separate from innovation or commercial growth. It provides the structure required to deploy data and AI responsibly, support customers across different regulatory environments and enter new markets with greater confidence.

In a region defined by rapid technological development and regulatory diversity, this ability to combine innovation with demonstrable control is becoming a significant competitive advantage.
Claire Hartley, Chief Compliance Officer Group DPO, Provenir

Claire Hartley

Written By

Chief Compliance Officer Group DPO, Provenir

Latest Resources

5 Questions Your Decisioning Platform Can't Answer (But Should)

5 Questions Your Dec...

5 Questions Your Decisioning Platform Can't Answer(But Should) Most
Brendan Deakin, Executive Vice President at Provenir

Confidence at Speed:...

Confidence at Speed:What Risk Leaders Are Actually Missing Most
BLOG Bharati Fernando

How to Change a Deci...

How to Change a Decisioning Model Without Raising a
Verifying the Invisible Subscriber

Verifying the Invisi...

Verifying the Invisible Subscriber How Accessing 1datapipe on the
FAQ

Decision Management ...

Decision Management Implementation FAQs for Enterprise Banks Implementing a
260817 - BLOG Closing Fraud Gap - FeatureIMG - EN 61409

Beyond Detection: Cl...
Beyond Detection:Closing the Fraud Prevention Gap Financial services providers
260726 - BLOG eyeDP - FeatureIMG - 61058

Beyond Data: Why Dec...

Beyond Data:Why Decisioning Needs Document Intelligence Financial services providers
Fraud in Telco: Provenir Experts Answer Frequently Asked Questions

Fraud in Telco: Prov...

Fraud in Telco:Provenir Experts Answer Frequently Asked Questions 1.

Continue reading

Latam Compliance Challenge for Decisioning

LATAM Next Compliance Challenge: Decisioning Accountability

From Data Protection to Decisioning Accountability:
What LATAM Regulation Means for Enterprise Lenders

The days of treating compliance, regulatory oversight and data protection as separate functions are coming to an end. 

Latin America is one of the most consequential growth regions in digital financial services right now. Banks, fintechs and lenders are using real-time data, alternative data and AI-enabled decisioning to expand credit access, strengthen fraud detection and make faster decisions at scale. 

But the compliance question has shifted. 

It is no longer sufficient to demonstrate that personal data was collected lawfully and protected securely. Organisations now need to explain how data influenced a decision, whether that data was reliable, and whether the outcome was fair, proportionate and properly governed. That is the transition underway across the region: from data protection compliance to decisioning accountability. 

The regulatory landscape makes this more complex. LATAM is not one market. Brazil, Mexico, Chile, Colombia and Peru are each developing their approaches to privacy, AI regulation, international data transfers and automated decision-making on different timelines and with different emphases.

A decisioning strategy developed for one country cannot be deployed unchanged across the region. Local legal requirements, regulatory expectations, data quality and market conditions all need to be reflected in how decisions are built, governed and explained.

This is where the architecture of a decisioning platform matters. 

Provenir provides a configurable decisioning environment that allows customers to maintain global consistency while adapting rules, workflows and strategies to the requirements of each market. Customers retain control over their legal grounds, data sources, risk policies and decisioning objectives, supported by visibility, access controls and auditability that regulators increasingly expect to see. 

Provenir’s broader compliance framework reflects this. ISO/IEC 27001 certification, contractual data protection controls, international transfer arrangements and subprocessor oversight are established elements. Provenir is also implementing an AI management framework aligned with ISO/IEC 42001 and emerging legal requirements across the markets we serve. That work strengthens governance around AI risk, accountability, transparency and lifecycle management — the areas where regulatory scrutiny is growing fastest. 

The opportunity in LATAM is real, but it is defined by more than speed. Organisations that can enter new markets, support financial inclusion and scale operations with demonstrably governed decisioning will be in a stronger position than those treating compliance as a retrospective concern. The next phase of LATAM regulation will test whether organisations can show that their data-driven decisions are lawful, secure, fair and explainable. That capability needs to be built into decisioning architecture from the start, not added to it later. 

Compliance is not a constraint on innovation in this region. It is the condition that makes sustained innovation possible. 

Claire Hartley, Chief Compliance Officer Group DPO, Provenir

Claire Hartley

Written By

Chief Compliance Officer Group DPO, Provenir


Latest Resources

5 Questions Your Decisioning Platform Can't Answer (But Should)

5 Questions Your Dec...

5 Questions Your Decisioning Platform Can't Answer(But Should) Most
Brendan Deakin, Executive Vice President at Provenir

Confidence at Speed:...

Confidence at Speed:What Risk Leaders Are Actually Missing Most
BLOG Bharati Fernando

How to Change a Deci...

How to Change a Decisioning Model Without Raising a
Verifying the Invisible Subscriber

Verifying the Invisi...

Verifying the Invisible Subscriber How Accessing 1datapipe on the
FAQ

Decision Management ...

Decision Management Implementation FAQs for Enterprise Banks Implementing a
260817 - BLOG Closing Fraud Gap - FeatureIMG - EN 61409

Beyond Detection: Cl...
Beyond Detection:Closing the Fraud Prevention Gap Financial services providers
260726 - BLOG eyeDP - FeatureIMG - 61058

Beyond Data: Why Dec...

Beyond Data:Why Decisioning Needs Document Intelligence Financial services providers
Fraud in Telco: Provenir Experts Answer Frequently Asked Questions

Fraud in Telco: Prov...

Fraud in Telco:Provenir Experts Answer Frequently Asked Questions 1.

Continue reading

RytBank

Customer Story: Ryt Bank

Ryt Bank is a Malaysia-based digital bank backed by YTL Group and Sea Limited. It positions itself as the first AI-powered bank, using its Ryt AI assistant (built on Malaysia’s ILMU LLM) to let you chat to pay bills, transfer money, and manage your account, targeting young professionals and frequent travelers with a simple, app-driven experience and transparent fees.
  • Industry
  • Region
  • Country

    Malaysia

  • Line of Business
  • Solution
  • Module
  • Infrastructure
  • ROI
  • Competition

Customer Timeline
Land MRR: $6,500 USD
Land PS: $16K USD
Expand MRR: ~$10K USD
Expand PS: $80K USD
  • Opportunity Created
    26th May 2023
  • Opportunity Won
    12th May 2025
  • Go-Live
    20th July 2025
    Technical Go-Live


    30 th August 2025
    Full Go-Live

  • Customer Expansion
    • Future: Property & Infrastructure-Linked Products
Initial Opportunity Details

  • Customer Challenge

    As a newly launched AI-powered digital bank, Ryt Bank needs to onboard and serve customers in seconds while maintaining robust risk controls and regulatory compliance. Early processes rely on a mix of internal systems, manual reviews, and hard-coded rules, making it difficult to support rapid product launches, dynamic pricing, and personalised credit decisions. This fragmentation slows time-to-yes, drives up operational effort, and limits the bank’s ability to fully leverage data and AI across the customer lifecycle. Ultimately, this impacts Ryt Bank’s ambition to scale quickly and deliver a seamless digital experience.
  • Provenir Impact

    • Smarter, AI-Driven Risk Decisions
      By combining Provenir’s decisioning platform with Ryt’s own AI models, Ryt Bank can assess creditworthiness in real time using a broader set of data points. This delivers more accurate approvals, reduces risk exposure, and supports consistent, data-driven decisions across the retail portfolio.
    • Faster Turnaround and Fully Digital Journeys
      End-to-end automation – from KYC and fraud checks to bureau calls and decision execution – has significantly reduced manual intervention, enabling near-instant decisions for onboarding and credit requests. This improves straight-through-processing rates, shortens time-to-yes, and enhances customer conversion in Ryt’s mobile-first channels.
    • Policy Compliance and Scalable Decisioning
      The solution enforces Ryt Bank’s credit, risk, and regulatory policies through configurable rules and strategies, ensuring consistent compliance with internal standards and Malaysian regulations. At the same time, it provides a flexible, scalable foundation to rapidly introduce new products and tweak policies as the bank grows.
  • Competitors

    FICO
  • Why We Won

    • Digital-Bank Ready, Cloud-Native Platform
      Provenir provides a modern, cloud-native decisioning platform designed for high-growth digital banks, supporting real-time decisions for onboarding, cards, and PayLater in a single environment.
    • Speed to Market and Business User Autonomy
      Our low-code configuration and reusable components allow Ryt Bank’s teams to rapidly design, test, and deploy strategies without heavy IT dependency, accelerating product launches and change cycles.
  • Pain Points

    • Need for instant, consistent decisions across onboarding
    • Difficulty orchestrating multiple data sources and analytics in one place
    • Limited agility to test and roll out new strategies, products, and risk policies
    • High operational overhead from manual reviews and fragmented workflows
Customer Growth

Growth Opportunities

Data Science Initiative: Collaboration with ILMU

Initial discussions have commenced between Ryt Bank, ILMU (YTL’s AI lab) and Provenir’s Data Science team to explore how ILMU’s LLM can be embedded into Provenir decisioning. This early collaboration focuses on use cases such as conversational credit applications, smarter risk insights, and automated policy explanations, laying the foundation for future AI-powered decision intelligence across Ryt Bank’s products.

Expansion

Property & Infrastructure-Linked Products

As YTL expands its townships, transport, and utilities footprint, Ryt Bank can create embedded financial products that are tightly linked to YTL’s property and infrastructure ecosystem. This includes tailored financing for YTL developments, bundled offerings that combine housing, utilities, connectivity, and banking, as well as subscription-style payments for transport and community services—all managed through the Ryt app. Such offerings deepen ecosystem stickiness, unlock new recurring revenue streams, and position Ryt Bank as the primary financial layer across YTL’s integrated developments.

OTHER CUSTOMER STORIES

Continue reading

Columbia Credit Union

Customer Story: Columbia Credit Union

Columbia Credit Union is a member owned financial co-op serving over 100K members and managing over $2 billion in assets. Founded in 1952, CCU provides a full suite of personal & business financial services, including checking/savings, consumer + auto loans, credit cards, Home services, and SMB lending. CCU is known for their strong community focus & are recognized for their deep commitment to member services. Credit Unions like CCU are focus on strong member experiences and financial inclusion for the geography and members they serve.
  • Industry
  • Region
  • Countries

    United States

  • Line of Business
  • Solution
  • Module
  • Infrastructure
  • ROI
  • Competition

Customer Timeline
Land MRR: $13,200
Land PS: $170K
Land DS: $0
Expand MRR: ~$17.5K
Expand PS: $84K
Expand DS: $71K
  • Opportunity Created
    August 6, 2020
  • Opportunity Won
    June 24, 2021
  • Go-Live
    Late 2020, Technical Go-Live

    Unknown Full Go-Live

  • Customer Expansion
    • In Progress:
      • Deposits New Account Opening – Fraud Checks
      • Account Management
      • Deposits New Account Opening Cross-Sell Model (Data Science)
      • Indirect Auto loan portfolio analysis and optimization (Data Science)
    • Future:
      Collections, SMB Lending, HELOC, Case Management
Initial Opportunity Details

  • Customer Challenge

    • Digital transformation, move to automated underwriting to reduce cumbersome onboarding and loan process and create a more frictionless experience for Members
    • Auto, Personal Loans, and Credit Cards will be focus 1st.
    • 4,500 apps / month, where only 20% / 900 are auto approved. 40% approved, with around 425 approvals per month. Biggest channel is auto dealer indirect channel.
    • Improved and enhanced member communication
      • Ability to automatically send “notifications” and/or “text messages”
      • Ability for two way communication with applicant via text messages
  • Provenir Impact

    • Automated Underwriting Process By implementing Provenir solutions in conjunction with incumbent Meridian Link, CCU could greatly increase their automated approval rates. This improved customer satisfcation, removed unnecessary friction for good users, and streamlined the UW process.
    • Reporting The ability to Easily generate “out of policy” reports to include the reason the loan was approved/declined was a significant piece for CCU.Ingesting the decision information based on where loan failed in the auto decision process provided insights for future improvement within the workflow
    • Member Communication Utilizing decisioning and data insights from Provenir to communicate value to their member community. Ability to automatically send “notifications” and/or “text messages” Ability for two way communication with applicant via text messages​
  • Competitors

    Meridian Link, NCINO
  • Why We Won

    • Speed to change / time to market.
    • The ability to auto decision based on numerous “if-then” scenarios – Ease of updating auto decision criteria
    • Object-oriented solution design enabled more complex, multi-threaded decisioning strategies
    • Reporting:
      • Easily generate “out of policy” report to include reason the loan was approved/declined
      • Decision information based on where loan failed in the auto decision process
  • Pain Points

    • Current automated approval at 20%; wants to get to 70%.
    • Limited member communication
    • Incumbent vendor’s slow and friction-filled delivery experience
Customer Growth

Growth Opportunities

TBD

Expansion

TBD

OTHER CUSTOMER STORIES

Continue reading

Metro Finance

Customer Story: Metro Finance

Metro Finance Pty Limited is an Australian-owned, independent finance provider specializing in vehicle and equipment loans. Since 2011, they have financed over $3 billion in loans, assisting over 50,000 customers. The company operates through a trusted broker network, offering both commercial and consumer finance solutions.
  • Industry
  • Region
  • Countries

    Sydney, New South Wales, Australia

  • Line of Business
  • Solution
  • Module
  • Infrastructure
  • ROI
  • Competition

Customer Timeline
Land MRR: USD 7,415
Land PS: $80K
Expand MRR: ~$15K
Expand PS: $300K
  • Opportunity Created
    2nd April 2024
  • Opportunity Won
    30th July 2024
  • Go-Live
    17th Feb 2025
    Technical Go-Live


    14th April 2025
    Full Go-Live

  • Customer Expansion
    • In Progress: PS – Novated Leases which is currently being scoped internally within MF
    • In Progress: DS – LLM solution discussions initiated
    • Future: PS – Consumer Vehicle Finance
Initial Opportunity Details

  • Customer Challenge

    Current underwriting processes are hampered by extended turnaround times, leading to low conversion rates and missed revenue opportunities. The existing solution, powered by Experian, is both costly and operationally heavy, limiting the organization’s ability to respond quickly to market demands. Additionally, delays in data retrieval from the Equifax Commercial Bureau in Australia further impact the speed and efficiency of credit decisioning, ultimately affecting the customer experience.
  • Provenir Impact

    • Smarter Risk Decisions with Greater Accuracy
      By integrating cumulative PD scoring and minimum Veda score logic, MetroFinance can better assess creditworthiness, reduce risk exposure, and ensure consistent, data-driven decisions across commercial vehicle finance.
    • Faster Turnaround with Automated Workflows The end-to-end automation — from exposure checks to bureau validation and model execution — has significantly reduced manual intervention, enhancing underwriting speed and improving customer conversion rates.
    • Policy Compliance and Scalable Decisioning
      The solution enforces internal credit policies through configurable rules (e.g., asset types, loan amount thresholds, applicant type), ensuring compliance at scale while remaining flexible to accommodate future requirements.
  • Competitors

    Experian & Ui Path
  • Why We Won

    • Proven Success Through an Extensive PoV and Sandbox Trial MetroFinance’s in-depth PoC validated Provenir’s system flexibility for rapid configurations, business-user autonomy, and improved underwriting speed. The platform demonstrated clear value in reducing friction and adapting quickly to changing requirements.
    • Integrated and Orchestrated by Design Provenir seamlessly connected with MetroFinance’s systems and data sources, enabling a unified and scalable decisioning infrastructure.
    • Strategic Alignment and Industry Expertise Provenir served as a trusted advisor, bringing deep financial services expertise and a strong understanding of commercial vehicle lending to align with MetroFinance’s long-term goals.
  • Pain Points

    • Complex rules, calculations and multi-applicants requirements
    • Incumbent solution’s inflexibility of interfacing with MetroFinance’s ecosystem, including broker portal, model services and data connections
    • Incumbent vendor’s slow and irresponsible delivery experience
Customer Growth

Growth Opportunities

  • Data Science Initiative: LLM Solution Discussions Initiated
    Initial discussions have commenced between MetroFinance and Provenir’s Data Science (DS) team to explore the application of Large Language Model (LLM) solutions. This initiative aims to identify use cases where LLMs can enhance decision intelligence, automate insights extraction, and drive smarter data-driven strategies. The collaborative dialogue marks an important step in extending advanced analytics capabilities across the organization, with a focus on innovation, scalability, and long-term business value.
  • Professional Services Engagement – Consumer Vehicle Finance
    As part of the ongoing strategic roadmap, Provenir’s Professional Services (PS) team is set to support the future implementation of a tailored decisioning solution for Consumer Vehicle Finance. This planned engagement will extend Provenir’s capabilities across a broader product suite, enabling MetroFinance to leverage a unified platform for both commercial and consumer lending. The initiative underscores Provenir’s long-term commitment to delivering scalable, flexible, and business-aligned decisioning solutions that support MetroFinance’s growth and diversification objectives.

Expansion

Professional Services Engagement – Novated Lease Workflow
Provenir’s Professional Services (PS) team is actively engaged with MetroFinance on scoping a tailored decisioning workflow for Novated Leases. This initiative is currently in the Statement of Work (SoW) discussion phase, with MetroFinance in the process of finalizing the agreement. It reflects the ongoing partnership and adaptability of Provenir’s platform to support emerging business needs. The PS team remains committed to co-designing a scalable and efficient solution that aligns with MetroFinance’s operational and strategic objectives in the novated lease space.

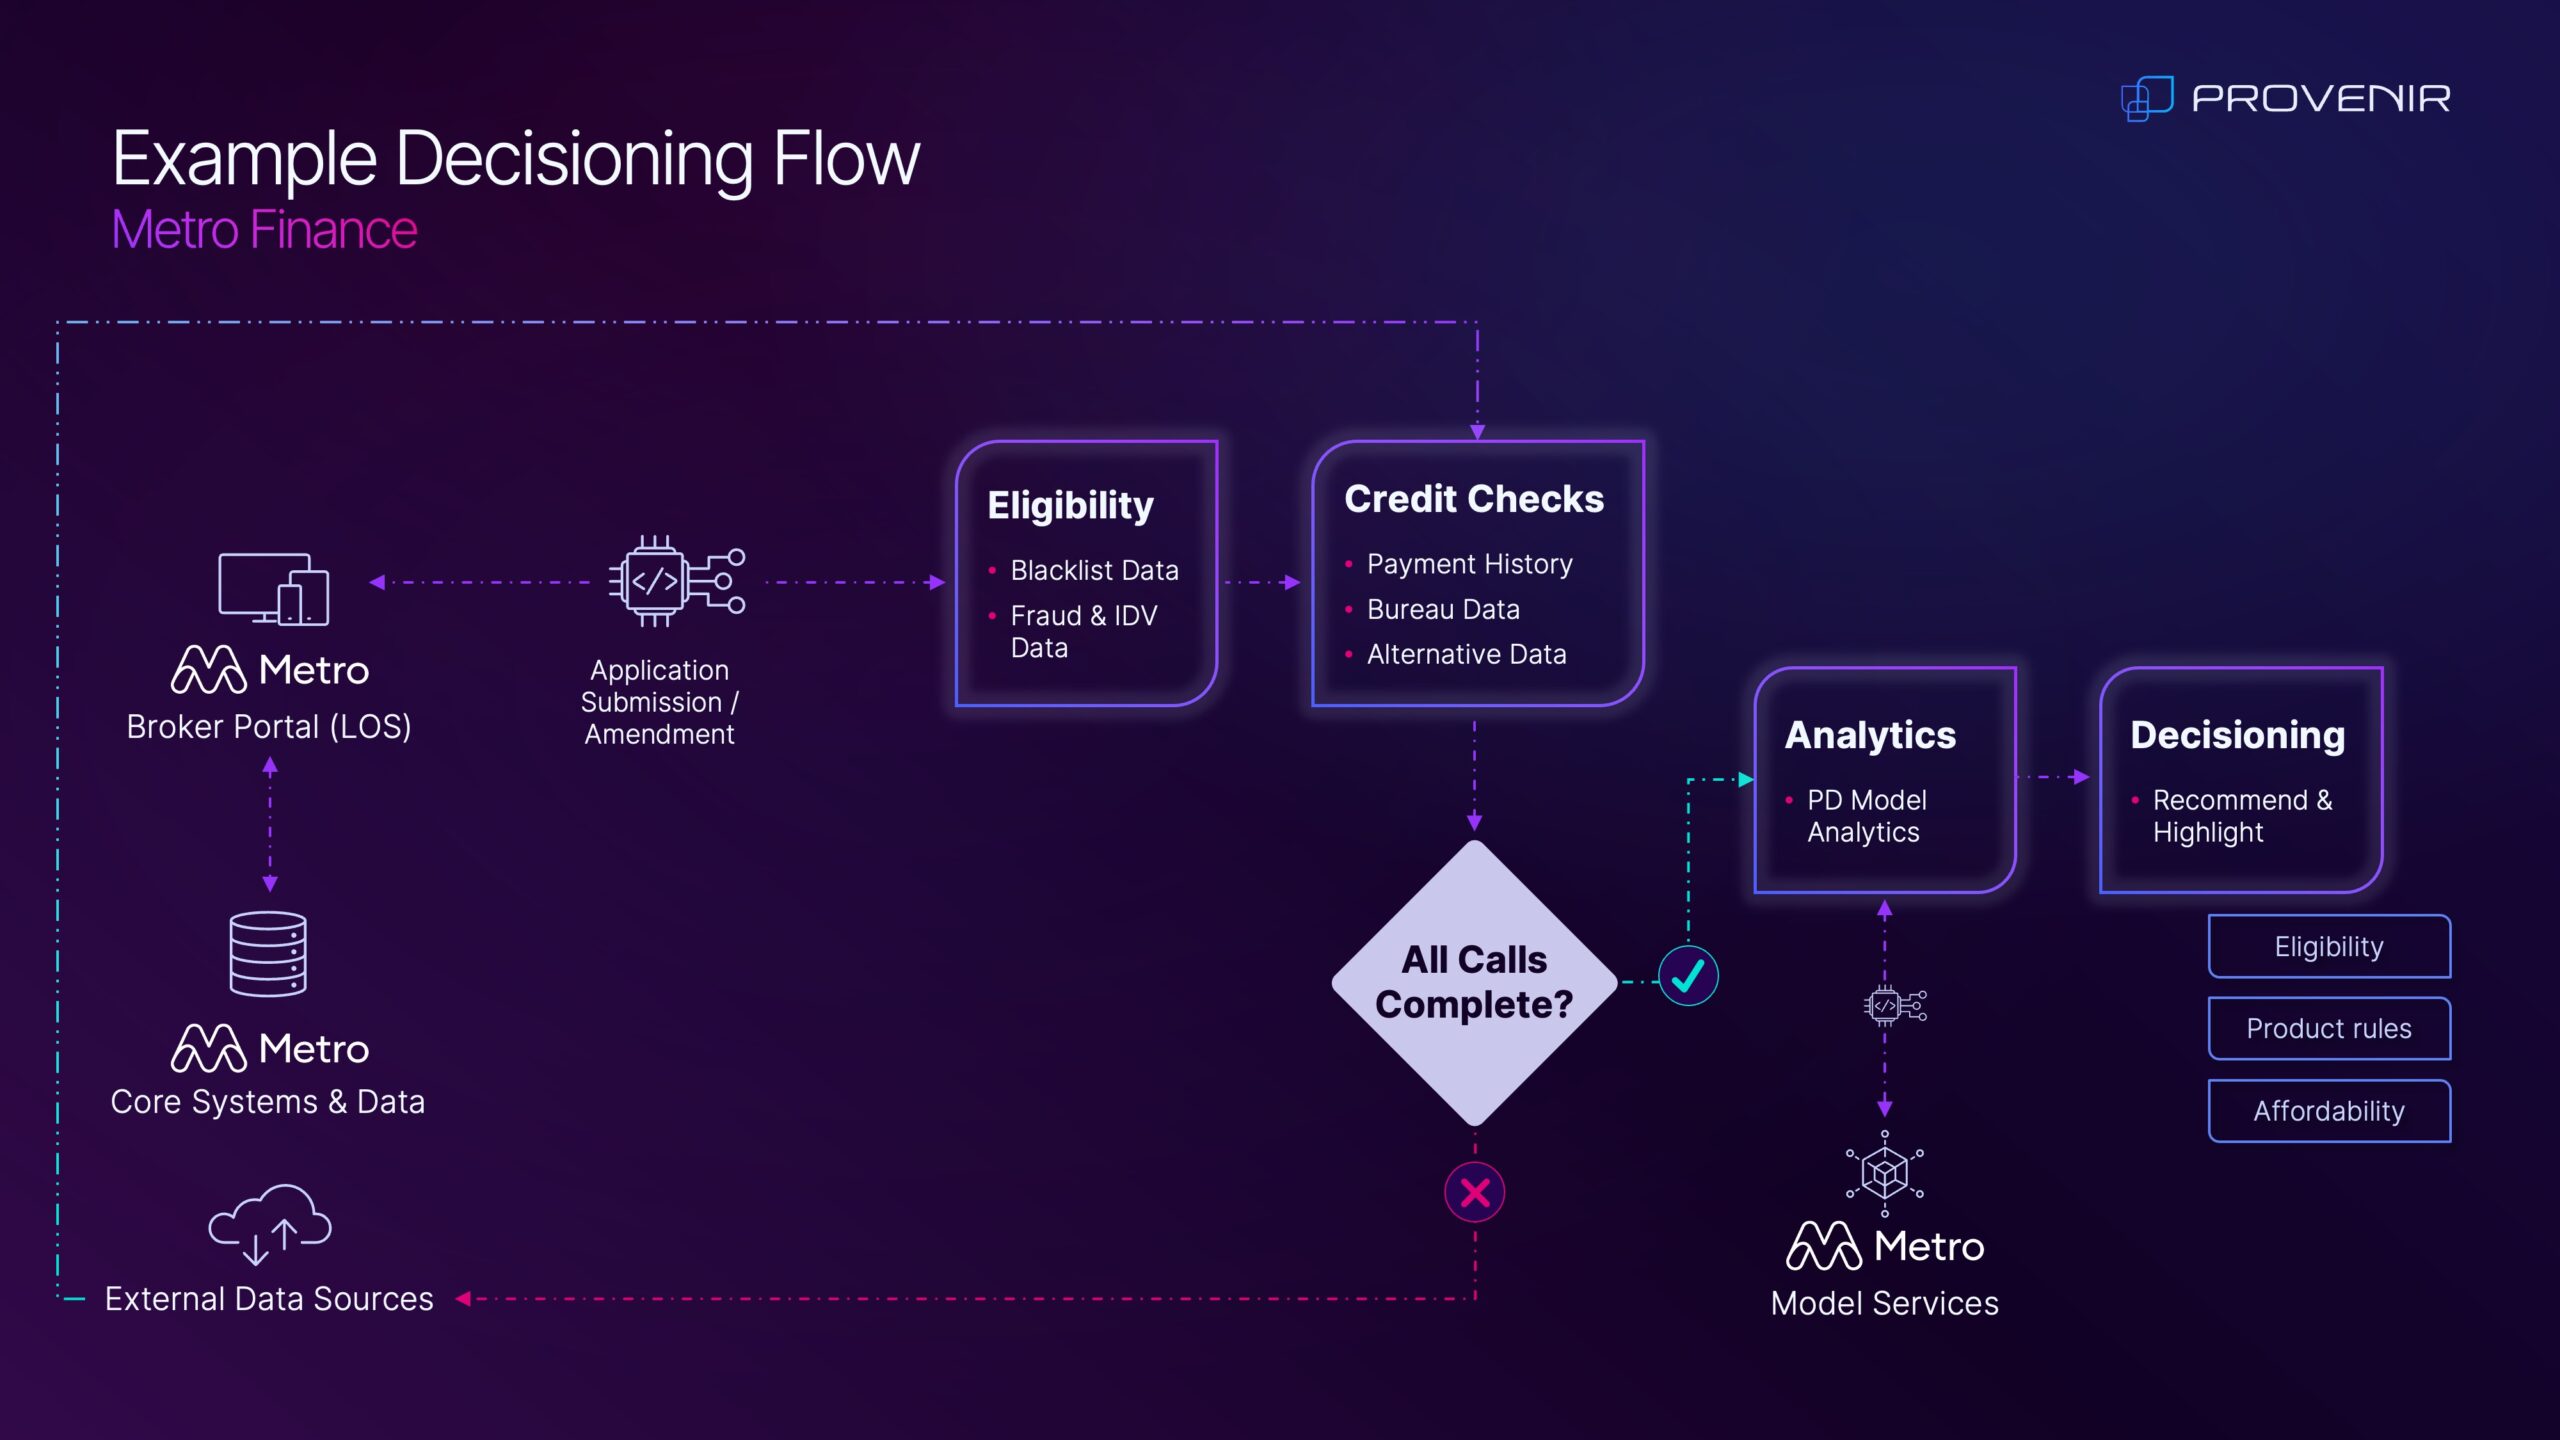
Metro flow

Example Decisioning Flows
  • New Application

    Decisioning

  • Eligibility

    Decisioning

    • Blacklist Data
    • Fraud & IDV Data
  • Credit Checks

    Decisioning

    • Payment history
    • Bureau data
    • Alternative data
  • Analytics

    Decisioning

    PD Score Verification
  • Decisioning

    Decisioning

    Recommend & Highlight
OTHER CUSTOMER STORIES

Continue reading

powerpay

Customer Story: PowerPay

powerpay

Powerpay, headquartered in Lima, Peru, operates as part of the BBVA Group, a leading global financial institution. Founded in 2022, the company was launched with the goal of providing flexible payment solutions to consumers. As a pioneer in the Peruvian market, Powerpay aims to become the first payment provider to offer Buy Now, Pay Later (BNPL) services, enabling users to split their purchases into installments. Customers can choose to pay in three interest-free installments or opt for six- or twelve-month plans with a small fee, using any credit card.

Beyond consumer benefits, Powerpay also supports merchants by helping them increase sales through financing options that attract new customers. The company is committed to innovation, ensuring users have greater control over their finances while making essential purchases. With an omnichannel approach, Powerpay seamlessly integrates with both physical stores and e-commerce platforms, adapting to the diverse needs of businesses in Peru.

  • Industry
  • Region
  • Countries

    Peru

  • Line of Business
  • Solution
  • Module
  • Infrastructure
  • ROI
  • Competition

Customer Timeline
Land MRR: $10,185
Land PS: $34,670
  • Opportunity Created
    January 17, 2024
  • Opportunity Won
    February 2025
  • Go-Live
    April 15, 2025
  • Customer Expansion
    • Application Fraud
    • Use of advanced analytics
    • Use of alternative data sources
    • Expansion to other countries
Initial Opportunity Details

  • Customer Challenge

    • Five-year aggressive growth plan focuses on automating consumer financing
    • Strict risk exposure control
    • The strategy includes AI-driven underwriting, enabling instant approvals and personalized loan offers
    • Expanding partnerships with retailers, while risk assessment ensures sustainable growth
    • Looking for scale operations efficiently, expanding its business while keeping default rates low and portfolio quality high
  • Provenir Approach

    N/A
  • Why it is Strategic for Provenir

    • First new logo in Perú
    • First BNPL project in the region
    • First opportunity in retail banking in the BBVA group
    • First project in cloud 2.0 in BBVA
  • Competitors

    Uflow – Decision Engine
  • Why We Won

    • Provenir’s enterprise capabilities
    • Support and good relationship with the BBVA group
    • Our flexibility and attempts to align ourselves with their current needs and limitations
    • Projecting a long-term relationship
    • Value selling approach
  • Pain Points

    • Lack of technology that allows automating the onboarding process.
    • Unable to scale international business
    • Lack of risk control
    • Struggling to operationalize advanced analytics model
OTHER CUSTOMER STORIES

Continue reading

charter logo

Customer Story: Charter

charter logo

Charter Communications is a leading broadband connectivity company and cable operator, headquartered in Stamford, Connecticut. With an annual revenue of $55 billion, Charter provides high-speed internet, video, mobile, and voice services to millions of customers across 41 U.S. states.

As a trusted provider, Charter serves 57 million homes and connects 500 million IP devices to its robust network. The company also powers businesses with 300,000 fiber-lit commercial office buildings, ensuring seamless connectivity and innovation. Recognized for excellence, Charter has been ranked #1 in customer satisfaction by JD Power within its peer group, reflecting its commitment to delivering high-quality service and superior customer experience.

  • Industry
  • Region
  • Countries

    United States

  • Line of Business
  • Solution
  • Module
  • Infrastructure
  • ROI
  • Competition

Customer Timeline
Land MRR: $62K
Land PS: $462K
Expand MRR: $100K
Expand PS: $250K
  • Opportunity Created
    June 28, 2024
  • Opportunity Won
    January 21, 2025
  • Go-Live
    Estimated July 2025
  • Customer Expansion
    • Collections/Delinquency Mitigation
    • Portfolio Management (upsell/cross sell)
    • TRMA Sponsorship
    • Case Study
Initial Opportunity Details

  • Customer Challenge

    • Charter has seen application fraud rates spike significantly over the past three years.
    • Antiquated systems prevented Charter from effectively mitigating application fraud
    • Experian FraudNet Solution cost over $1M a year to support and was ineffective.
    • New senior executive team hired to rebuild Charter fraud onboarding infrastructure
    • Charter Data Science team was handcuffed by poor analytics, testing capabilities, and decentralized workflow tools.
  • Provenir Approach

    Profiling Engine

    Aggregation of specific values over a time period.

    • “Grouping of Activity” / “Buckets of Behavior”
    Examples:
    • IP Address 168.192.1.1 has been on 10 transactions over the past 6 hours
    • Location 123 has had a median order amount of $5,222 over the past 180 days
    Python Model Deployment

    Provenir provides the Charter Data Science team a platform to deploy, execute, test, monitor models they build to detect Fraud and Risk.

  • Provenir Impact

    • Reduced customer friction and losses, while optimizing operations through a stable, reliable, and scalable platform to support analytics and reporting needs.
    • Fraud and credit abuse controls prior to order submission will enable more accurate real-time decisioning.
    • $1M immediate annual cost reduction with the elimination of the Experian FraudNet tool.
    • The platform will enable risk assessment functionalities like testing rule performance and fraud decisioning through advanced ML models
    • Centralized Rule and Model Governance
  • Competitors

    Experian (incumbent), FICO, DataVisor, Socure, Visa (risk product) and Pega
  • Why We Won

    • Provenir Solution: Provenir Profiling Engine provided the most compelling/complete solution for Charter
    • Our Team: Fraud Expertise + Implementation Certainty
    • Decision Intelligence and Advanced AI/ML
      Centralized Rules and Model Governance
  • Pain Points

    • Decentralized fraud controls
    • Poor Analytics and Reporting
    • Infrastructure Downtime
    • Inability to leverage AI and Advanced Learning models
Customer Growth

Growth Opportunities

Organic Volume Growth – Charter’s expecting significant geographic expansion over next 3-5 years.

Expansion

  • Portfolio Management/Account Management
  • Collections – Charter has seen a rise in delinquencies and customer churn
Example Decisioning Flows
  • New Application

    Decisioning

    Orders received for two channels:

    1.Ship to Home
    or
    2.In Store

  • Internal/external Data Calls

    Decisioning

    Data Vendors

    • Ekata
    • SentiLink
    • Datafiniti
    • Nuance
    • RevSprings
    • UPS/FedEx
    • Citrix
    • Authentic ID
  • Real-Time Fraud Checks

    Decisioning

    Rules and Lookups

    • Negative List
    • Velocity Checks
    • Email, Billing, Device, Attempts, etc.
    • Feature Aggregation
    • Blacklist
    • Valid/Deceased SSN
    • Fraud Prevention Scenarios
    • SMB Orders
    • Positive Lists
  • Scoring and Risk Models

    Decisioning

    Analytical Models

    • Models built by Charter Data Scientists in KC
    • Champion / Challenge
    • Ongoing Feature Engineering
  • Manual Review Exceptions

    Decisioning

    Alert Review

    • Red / Yellow / Green Risk Assignment
    • Fraud, Credit, Sanctions, Affordability Analyst and Underwriter Reviews
OTHER CUSTOMER STORIES

Continue reading

instabank

Customer Story: Instabank

instabank

Instabank, the Nordic challenger bank, has been redefining the banking experience since its full digital launch in Autumn 2016. Their passionate team is dedicated to improving banking for both corporate and private customers, challenging established norms, and providing flexible solutions that simplify complexity.

  • Industry
  • Region
  • Countries

    Nordics

  • Line of Business
  • Solution
  • Module
  • Infrastructure
  • ROI
  • Competition

Customer Timeline
Land MRR: $5,500
Land PS: 0
Expand MRR: $18,045
Expand PS: $22,500
  • Opportunity Created
    December 2016
  • Opportunity Won
    2017
  • Go-Live
    June 2017
  • Customer Expansion
    • Originations SME
    • Consumer Loans, 26-6-2017
    • Cloud 1, 2017
    • Cloud 1 expansion -2021
    • Cloud 2.0 Migration – 2022
    • Cloud 2.0 Expansion – 2024
Initial Opportunity Details

  • Customer Challenge

    Since opening its digital doors in 2016, Instabank has become a disrupter in the Nordic banking community. One of its key products is instantly approved, direct-to-consumer, unsecured loans. The bank also partners with retailers to provide real-time point-of-sale loans to their customers. Initially, the bank used a traditional lending solution with thousands of lines of code. As a digital “challenger” bank, Instabank needed a platform that would not only enable instant decisioning, but also offer the flexibility and scalability to support the company’s rapid growth.

  • Provenir Approach

    Provenir provided some key benefits from implementing the platform.

    • The Provenir Risk Decisioning Platform delivers a flexible solution for Instabank’s digital banking services.
    • Automated process gathers data from multiple sources and decisions each loan application in a minute.
    • Flexible, business-focused design tools substantially reduce time and costs for developing country-specific banking solutions.
    • Pre-configured integration adaptors enable real-time data gathering from Experian and a European property data provider.
    • Cloud-based implementation enables rapid deployment with controlled costs.
  • Provenir Impact

  • Competitors

    Experian
  • Why We Won

    • Ease of use
    • Data integration
    • Ability to onboard new product lines
  • Pain Points

    • Current solution is mainly hard coded
    • Data integration is cumbersome
    • Lack of in-market support
Customer Growth

Growth Opportunities

  • Looking to grow and expand the business lines
  • Deposit account
  • Financing of cars and boats
  • Credit cards +
  • Debit Cards
  • Sales Financing
  • Factoring

Expansion

Cloud 2 Expansion

Example Decisioning Flows
  • New Application

    Decisioning

  • Identity & Verification Checks

    Decisioning

    • Experian
    • emailage
  • Enrichment

    Decisioning

    • nudata
    • IDology
    • SentiLink
  • High Risk Patterns & Scoring

    Decisioning

    Application fraud
    Rules and AI Model

    Auto Accept
    Auto Decline
    Referrals

  • Fraud Investigation

    Decisioning

    Case Management
OTHER CUSTOMER STORIES

Continue reading

telia company

Customer Story: Telia

telia company

Telia Company is a leading telecommunications and mobile network operator primarily serving the Nordic and Baltic regions, with operations extending to the other parts of Europe and Asia.
Established in 1853, Telia has evolved into a modern telecommunications company, providing a wide range of services including mobile and fixed line telephony, internet, digital television and enterprise solutions.

After successful engagement with Telia Finance for many years on Cloud Platform, at the end of 2022, Telia Company, the parent of Telia Finance decided to go with Provenir for their own country specific entities who operate separately and who also provide telecoms products with credit. With a focus on innovation and sustainability, Telia is committed to shaping the digital future and enhancing connectivity for individuals and businesses.

  • Industry
  • Region
  • Countries

    Sweden, Finland, Denmark, Norway

  • Line of Business
  • Solution
  • Module
  • Infrastructure
  • ROI
  • Competition

Customer Timeline
Land MRR: $40K
Land PS: €250K
Expand MRR/PS: N/A
  • Opportunity Created
    May 2022
  • Opportunity Won
    December 2022
  • Go-Live
    TBD
  • Customer Expansion
    • TBD
Initial Opportunity Details

  • Customer Challenge

    Telia decided to adopt a new standardized credit granting process that forms the basis for different products and services in B2C and B2B areas. The key is to establish a platform on which different credit decisioning processes can be achieved with:

    • Increased business agility, adaptive response to changes in market and customer behavior
    • Easy to integrate with external & internal systems to enhance decision making quality
    • End-to-end risk management & compliance
    • High performance & easy to scale
    • Cost efficiency on a single platform
    • Support & flexibility for multi-product, multi-country type complex design

    The ambition is to complete the roll-outs of this credit decisioning initiative by EoY-23 across multiple countries to improve time-to-market and reduce customer friction for better customer experience

  • Provenir Approach

    • Provenir Adaptor Technology: to collect data and communicate various internal & external systems/sources
      • UC, Bisnode, Phone & Email services
      • CRM, Finance, Billing etc.
    • Visual & Quicker build for rules & calculations
    • Optimize the promotion of reusable building blocks (flows) in a flexible design context in multi-step and multi-level decisioning
    • Ease of analytical asset operationalization
    • Handling exceptions thanks to Provenir versatile Case Mgt. on Salesforce
  • Provenir Impact

    • Quicker time to market (<3 months)
    • Increased FTE productivity
    • Improved Operational Efficiency (response <6 secs)
    • Faster roll-outs across countries
  • Competitors

    Experian, FICO
  • Why We Won

    • Strong existing customer relationship from Telia Finance
    • Provenir’s flexibility, business friendly interface, support for reusable building blocks (micro-service oriented)
    • Presales and PS collaboration to meet every single custom requirement via a tailored demo artifact + detailed workshops to address all business, functional and technical aspects forming a strong trusted advisor state
    • Smart deal strategy to make the financial model attractive esp. for multi country multi brand.
  • Pain Points

    • Easy to change, low-code solution for agility & responsiveness
    • Quick access to data
    • Simplify multi-product, multi-brand, multi-country complex design pattern
Customer Growth

Growth Opportunities

The successful engagement & delivery means that now Provenir and Telia are in conversations for further expansion:

  • Telia Company Norway
  • Telia Company other countries

Expansion

Telia Finance offered loans & credits for telecom products. With the Telia company expansion in 2022 our successful roll-out starts with Telia Finance Denmark for B2B and B2C products (mobile, broadband, TV) in risk-based pricing and limit, which is later planned to be followed by:

  • Telia Finance Sweden (mid-June 24)
  • Telia Finance Finland (Q3-24)
  • Telia Finance Norway (Q4-24)
Example Decisioning Flows
  • New Application

    Decisioning

  • Pre-Scoring

    Decisioning

    (Credit Policy Rules & Internal Payment History)

    • Application Data
    • Invoice information (Order & Payment History)
    • Population Register Data
    • Phone & Email Service
  • External Scoring

    Decisioning

    (Fraud, AML, Sanctions, Credit Bureau)

    uc sweden
    d&B
    (formerly Bisnode)

    • Fraud, sanctions, AML scores
    • Disposable income calculations
    • Bureau generic models
  • Customer Specific Scoring Models

    Decisioning

    Telia custom scoring model with internal Telia data & external data combined (fraud, bureau, register, application data involved)

  • Risk & Fraud Investigation

    Decisioning

    Case Management
    (On Salesforce)
OTHER CUSTOMER STORIES

Continue reading

Customer Story: Admiral Money

Admiral Money is the lending subsidiary of the Admiral Group, a UK-based multi-national financial services company, set up in 1993 to specialize in car insurance. Admiral has since expanded into multiple insurance, personal finance, price comparison and legal offerings.

As of December 2023, the Admiral Group recorded 9.7 million customers, 11 thousand employees and £4.8 billion turnover worldwide, with presence in markets across EMEA, North America and South Asia.

  • Industry
  • Region
  • Country

    UK

  • Line of Business
  • Solution
  • Module
  • Infrastructure
  • ROI
  • Competition

Customer Timeline
Land MRR: £17,350
Land PS: £166,464
Expand MRR: £30,836
Expand PS: £107,250
  • Opportunity Created
    20/08/2018
  • Opportunity Won
    19/11/2019
  • Go-Live
    15/05/2020
  • Customer Expansion
    • 03/09/2020 – Additional DEs
    • 23/10/2020 – ConTe.it (Italian subsidiary)
    • 03/10/2022 – Additional non-Production environment for ConTe.it
    • 20/12/2022 – Renewal 2022
    • 07/02/2024 – HP Integration and Warranty Cover
Initial Opportunity Details

  • Customer Challenge

    Admiral Money was using Equinity Pancredit decision engine and case management solution, a rather rigid and monolithic solution. After several initial meetings and demos, they decided to replace the decisioning portion with an agile decision engine that would give them the flexibility to make changes within the business, efficiency to test and operationalize new strategies and models, as well as simplify accessing new data sources.
    The initial meetings were key to convincing them to replace their existing decision engine when they realized it was not providing them the functionalities listed above.
  • Provenir Approach

    Initially, our solution mirrored what they had previously implemented in the former engine:
    They used us for Unsecured Personal Loans quotes, and kept applications as well as the underwriting system in Pancredit. However, in late 2022 they started to move away from their legacy vendor and asked us to help them re-build the configuration to include Auto Loans with different flavors (Hire Purchase and Personal Contract Purchase), as well as applications. They needed to meet tight deadlines, and thus our PS team became an extension of the three-person Admiral team to support them for this purpose. We successfully delivered this new implementation, and enabled them to have a multi-product decisioning approach.
  • Provenir Impact

    • Ability for their three-person team to autonomously implement changes to their decision logic.
    • Speed to market: 5 months to conduct a successful implementation.
    • Multi-product decisioning approach with distinct scoring logic, pricing models and personalized recommendations to the end customer (customers could receive additional product recommendations from what they originally applied for and choose what best suits them). The Admiral team envisioned this approach as they grew accustomed to using Provenir and realized the possibilities it gives them in terms of implementation.
  • Competitors

    DecisionMetrics (now part of TransUnion) and Zoot.
  • Why We Won

    We scored very high in the initial RFP, although our high cost and the lack of an out-of-the-box case management system were against us. Finally, we proved over the course of two on-site workshops that we excelled in all the areas for improvement they had identified.
  • Pain Points

    • Agility for the business to make changes
    • Ease of connection to data sources
    • Capable of hosting pricing models
    • Use of different parameters for different scenarios
    • Microservices-oriented
Customer Growth

Growth Opportunities

  • Flipping from a DE-based to a transaction-based commercial model.
  • Collections processing and pre-disbursal checks, after having duly identified volume and value.
  • Use of Ekata services through Provenir.
    Auto-scaling capabilities to handle highly spikey volumes.
  • Switching to Cloud 2.0 at some point in time, which will come as Admiral Money continues to expand their use of Provenir, so as to be able to justify the PS investment.

Expansion

The relationship with Admiral has largely expanded since the initial opportunity in 2019. Firstly, we increased the contract value by adding more DEs. Then, we signed a new contract with Admiral’s Italian subsidiary, ConTe.it. Further, we successfully secured a significant uplift in the MRR when renewing the main contract in 2022. Last, but not least, starting in late 2022 and throughout 2023 we re-built their configuration to include applications (and not only quotes) and an additional loan product (Auto loans).
Example Decisioning Flows
  • New Application

    Loan

    Admiral website and price comparison websites

    Admiral Service Layer

    Orchestrating all the calls between the different systems

  • Processes

    Loan

    • 1. Quote Process

      • Eligibility Checks
      • Pricing calculated through Excel models
      • Calls to TransUnion and Equifax Consumer Credit Bureaux
    • 2. Affordability, Fraud and KYC Calls

      • TransUnion Affordability Check
      • Moneyhub Open Banking
      • Synectics SIRA
      • TransUnion CallValidate
      • Credit Bureaux calls moving here in the future
    • 3. Application Process

      • Further eligibility checks
      • Affordability, fraud and KYC assessments based on the data orchestrated by the Admiral service layer
    • 4. Manual Underwriting

      • In-house built Underwriting platform
      • Re-submission of the application into Provenir (Application Process)
  • XML & S3

    Loan

    Application Process: Send XML to AWS S3 if Referral or Declined.

    Retrieve XML from S3, send to 4. Manual Underwriting

OTHER CUSTOMER STORIES

Continue reading